

Jump To
By Edita Abrudeanu, Founder & Principal Broker — Professional Insurance Experts, LLC
Architects and Engineers Professional Liability Cost: 22 Real Pricing Examples
Google “How much does architects and engineers professional liability insurance cost?”
You’ll get the same answer everywhere:
It depends.
And to be fair, it does.
It depends on your discipline. Your revenue. Your projects. Your limits. Your deductible. Your claims. Your contracts. Your quality controls.
I already wrote the article explaining all of that.
If you want the full breakdown, read Factors That Affect Architects and Engineers Professional Liability Premium first.
Helpful?
Yes.
Still slightly frustrating when your renewal lands and you’re trying to figure out whether $4,500, $14,500, or $45,000 is remotely normal?
Also yes.
So I decided to give you the part most pricing articles leave out.
Actual numbers.
01. I Pulled 22 Actual A&E Pricing Examples
I compiled 22 professional liability pricing scenarios for architecture and engineering firms from 2025–2026.
Then I removed the private information and kept the variables that make the price useful:
- Revenue
- Employees
- Type of work and project mix
- Limits
- Deductible
- Claims history
- Premium
Eleven architecture firms.
Eleven engineering firms.
Different sizes. Different work. Very different premiums.
This is not a rate sheet. It is not a market average. And it is definitely not a promise that your firm should pay the same amount.
But it should give you something more useful than “it depends.”
A place to start.
02. How to Find the Closest Match
Start with your profession and revenue.
Then slow down.
Look at the work. Look at the project mix. Look at the limit and deductible. Check the claims column.
The firm closest to your revenue may not be the firm closest to your risk.
03. Architecture Firm Pricing Examples
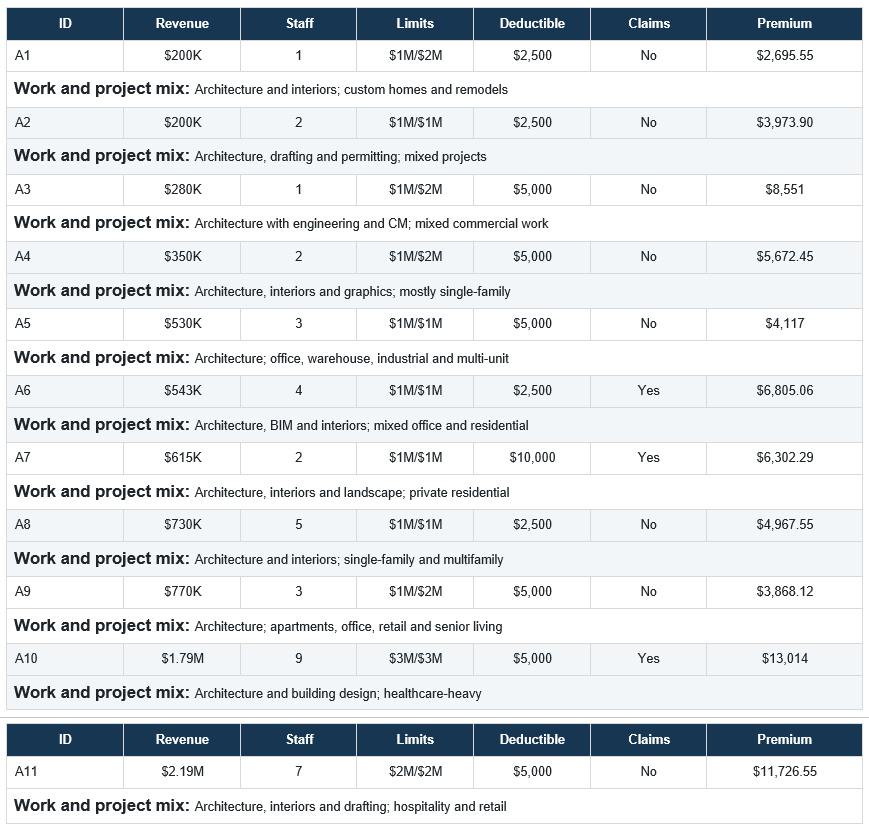
The architecture premiums run from $2,695.55 to $13,014.
But the range is not the interesting part.
Look at A1 and A3.
Both are one-person firms. Both carry $1 million/$2 million limits. Neither reports a claims history.
A1 pays $2,695.55.
A3 pays $8,551.
More than three times as much.
Why?
The table gives us clues: different revenue, deductible, services, and project mix. It does not give us the underwriting file, policy wording, carrier, contracts, or every detail behind the quote.
That is exactly why “my friend pays less” is not a pricing strategy.
04. Engineering Firm Pricing Examples
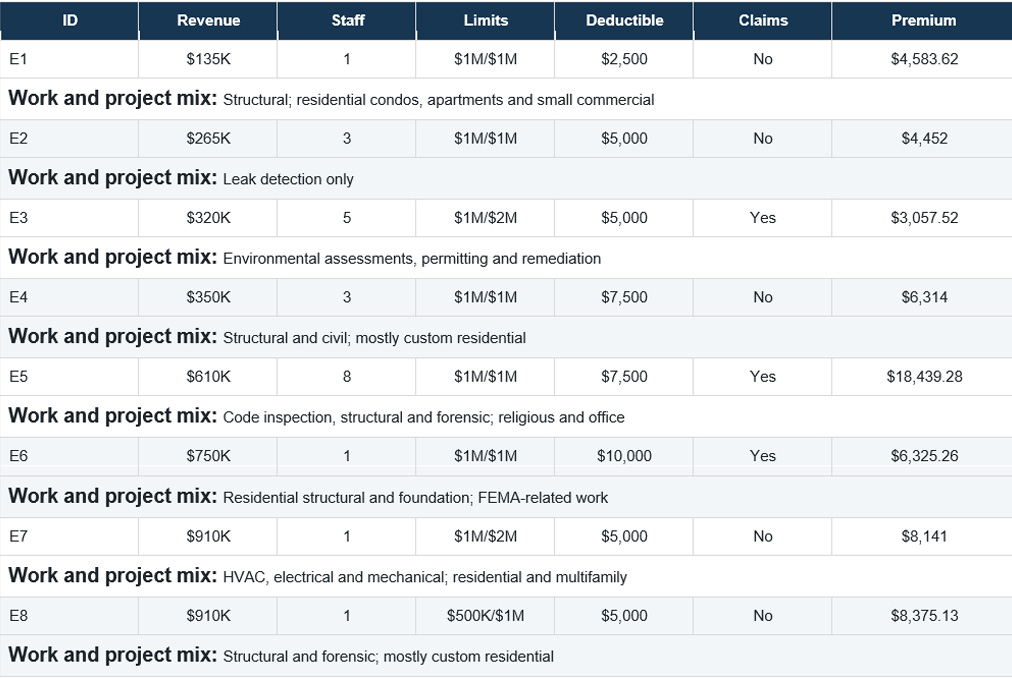
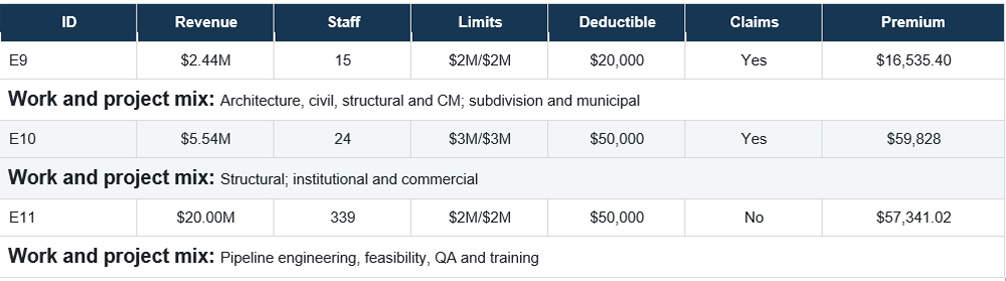
Engineering is where the spread gets wild.
$3,057.52 at the low end.
$59,828 at the high end.
And no, revenue does not explain the whole thing.
E3 and E4 report almost the same revenue: $320,000 and $350,000.
E3 pays $3,057.52.
E4 pays $6,314.
More than twice as much.
Then you look closer.
Environmental consulting versus structural and civil work. Different limits. Different deductibles. Different projects. Different underwriting stories.
05. What These Numbers Can Actually Tell You
They can give you a gut check.
If your one-person architecture firm pays $22,000 for $1 million limits, this table should make you ask questions.
If your structural engineering firm pays $5,000, it should also make you ask questions.
Different questions.
The first firm may be paying too much. Or it may have claims, difficult projects, broad services, unusual contracts, or coverage the cheaper examples do not have.
The second firm may have a great deal. Or a narrow coverage form. Or restricted work. Or a retroactive date that leaves old projects behind.
A low premium is not proof of a good policy.
A high premium is not proof you are being overcharged.
The number tells you where to look. The policy and underwriting details tell you what it means.
06. Four Rules for Comparing Your Firm
- Match the work before the revenue. A $1 million structural firm and a $1 million environmental firm are not the same account.
- Match the coverage. Compare limits, aggregate, deductible, prior acts, defense treatment, professional-services wording, and exclusions.
- Do not treat claims history as a yes-or-no verdict. The date, severity, status, and corrective action matter.
- Use the table to start the conversation, not end it. A real comparison requires the application, quote, policy form, and endorsements.
07. Want the Full Explanation of What Changes the Price
I deliberately did not repeat the entire underwriting lesson here.
For the detailed explanation, read Factors That Affect Architects and Engineers Professional Liability Premium. It covers discipline, projects, firm size, claims, contracts, risk management, revenue, and policy structure.
Engineering firms can also read How Much Does E&O Insurance Cost for an Engineering Firm for a discipline-specific breakdown.
This article has a different job.
Show you the numbers.
08. Want to Know Where Your Firm Lands
Send PIE your current professional liability policy and renewal proposal.
We’ll compare the premium, limits, deductible, prior acts, wording, exclusions, and available market options against the work your firm actually performs.
Because “it depends” may be true.
But you still deserve a real answer.
The examples above are anonymized and educational. They are not quotes, guarantees, legal advice, or a substitute for reviewing the actual policy, endorsements, application, contracts, facts, jurisdiction, and carrier interpretation.